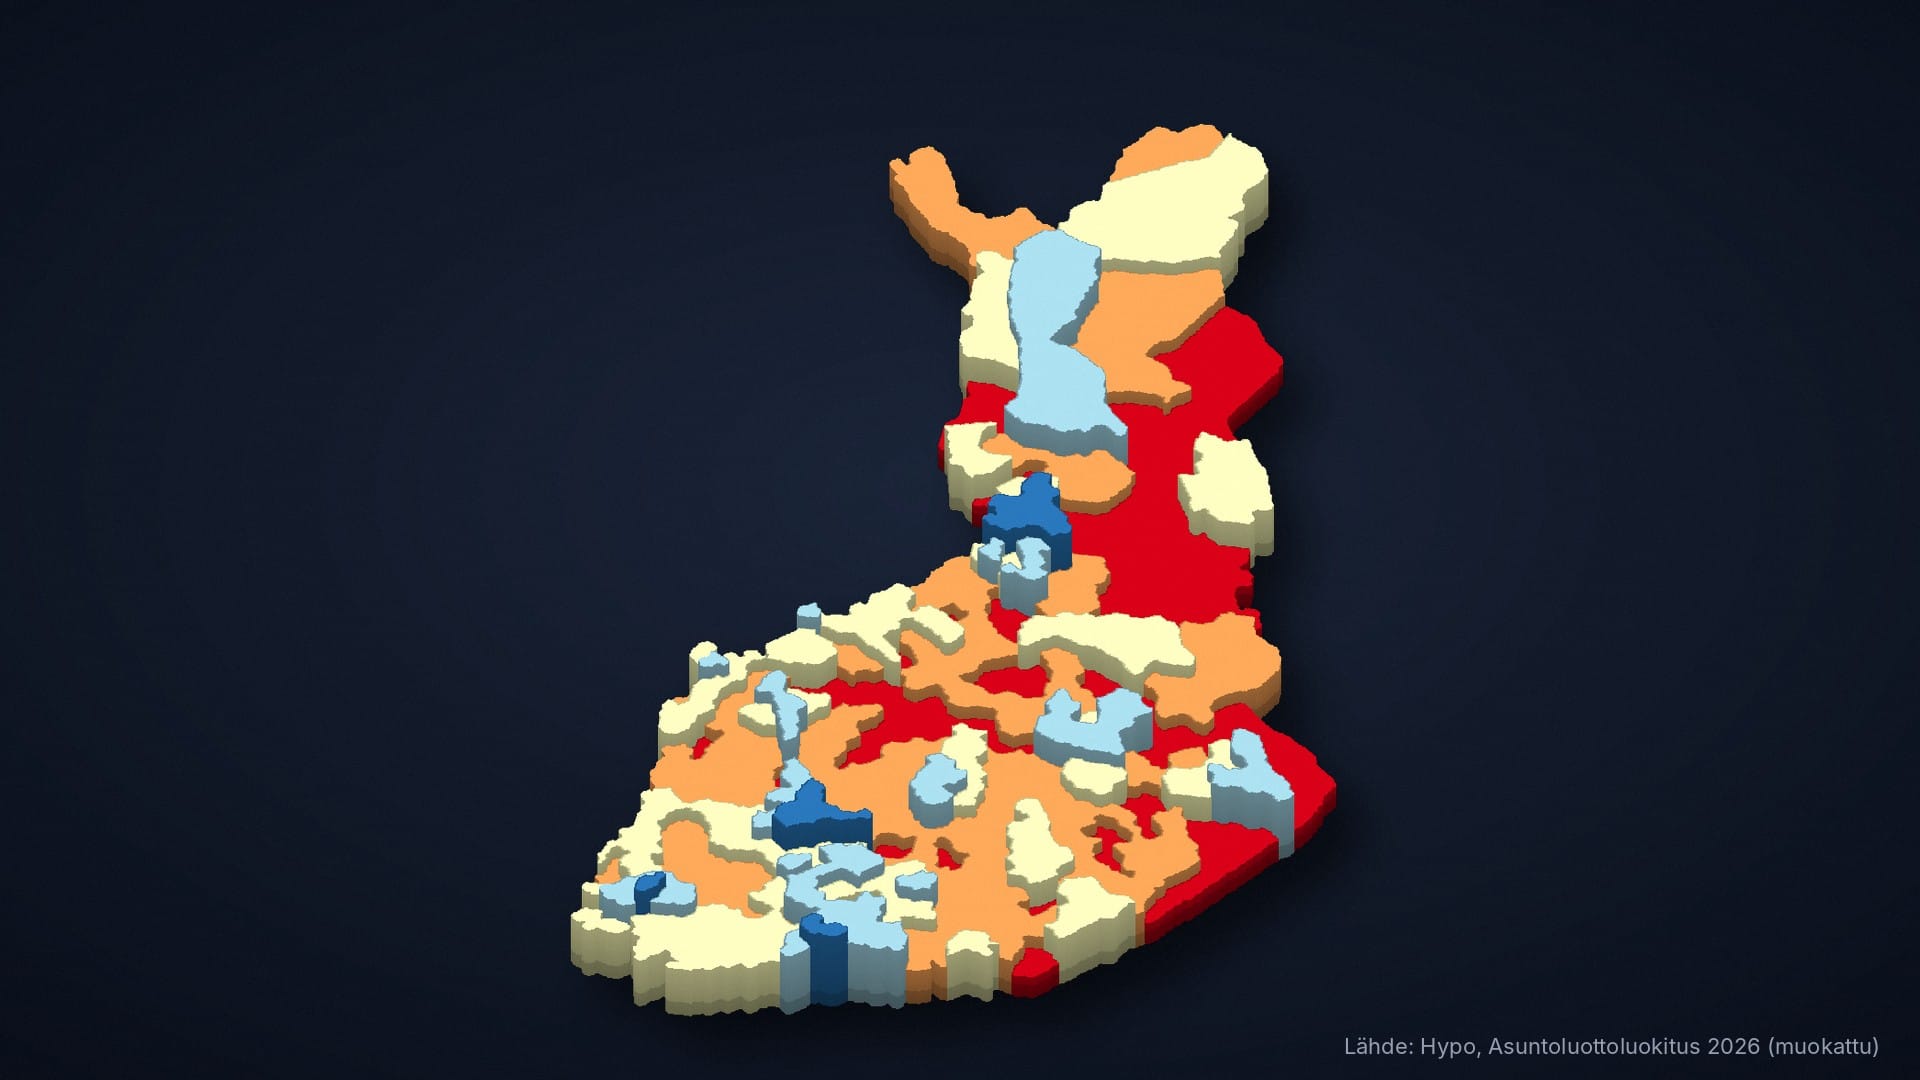
Housing market divergence is not a new phenomenon, but it has now taken a concrete form that cannot be ignored. In Hypo’s October 2026 housing credit classification, only 10 municipalities reach the A category. In the previous update, 13 municipalities achieved A level. At the same time, 61 municipalities fall into the C range, meaning the red-shaded risk zone. These figures tell you directly what a buyer should ask themselves before signing anything.
What the classification actually means for a buyer
Hypo’s classification measures regional risks and prospects. It is not a matter of opinion – it has now been calculated for the seventh time across all mainland Finnish municipalities. The A category means strong markets. The C range means that demand is weak, prices may fall, and liquidity is poor.
In practice, this means two things. First, resale value is not a given. Second, banks price the loan-to-value risk partly based on location. If a purchase is made in a C-area municipality, the collateral value may be tighter than the buyer expects.
At least 45 municipalities reach BBB or above, and they are home to 61 per cent of mainland Finland’s population. This means that the majority of Finns live in areas with a reasonable market situation. But it also means that nearly 40 per cent of the population lives in municipalities where market conditions are clearly weaker.
Five things to check before making an offer
This is not about saying you should never buy a property in a C-area. It is about making sure the buyer knows what they are agreeing to. These five points are worth going through before submitting a binding offer.
- The municipality’s classification on Hypo’s scale. Find out whether the property is in an A, B, C, or intermediate-level municipality. This information is public and tells you more than the seller’s asking price.
- Actual transaction prices in the area. Not asking prices, but actual completed sales. Look at how much prices have moved over the last two years. The trend tells you more than any single price per square metre.
- Time on market in the immediate area. Long selling times indicate a lack of demand. If comparable properties have been on the market for a long time, that is a signal about liquidity – that is, how easily you will be able to sell the property later.
- Population trends and migration. A municipality people are leaving is a different proposition to one people are moving to. Population decline puts downward pressure on prices in the long run, and no individual property is immune to that.
- The bank’s collateral valuation practice in the target area. Ask the bank directly how they value collateral in that particular municipality. In some municipalities, the collateral value can be significantly below the purchase price, which affects the mortgage amount.
Market conditions have improved, but not evenly across all areas
Juhana Siljander, a team leader at the Bank of Finland, has noted that the situation since summer has not been as bad as previously thought. Revised figures from Statistics Finland show that transaction volumes grew considerably more during January to September than had been reported earlier. In September, prices rose month-on-month in the Helsinki metropolitan area and in major cities.
But this trend does not cover the whole country. October transaction volumes were still around 10 per cent below last year’s level. And housing market divergence means precisely that, even if Helsinki moves into positive territory, the same does not apply to a C-range municipality three hours away.
Hypo’s housing market review from May 2026 states that population growth, income development, and the collapse in construction support price development in growth cities. Not elsewhere. That is an important distinction.
Loan-to-value risk is concrete, not theoretical
When a bank grants a mortgage, it looks at the collateral value. Collateral value is calculated on the basis of the estimated market value, but the area’s risk profile also influences how conservatively the bank makes its assessment. For a property in a C-area, this can mean that the down payment requirement effectively rises without anyone saying so out loud.
If the property later goes to a forced sale, or in a situation where the owner needs funds quickly, C-area markets do not flex in the same way as A-area markets. This is a risk worth calculating in advance, not in hindsight.
The checklist is not a barrier to buying
A buyer’s checklist does not mean waiting for a perfect property or a perfect area. It means making a decision based on knowledge rather than wishful thinking.
In an area of weak demand, resale value and liquidity are in a different league to those in a growth centre. This risk may be one you consciously accept, especially if it is already reflected in the purchase price. What matters is that it has been worked through before the transaction. Regional risks are based on measurable factors, but there is always uncertainty around future market developments, and no classification guarantees what lies ahead.
Are you confident about the market conditions in your target area?
An area's classification directly affects resale value and the risk level of your mortgage. Find out where things stand before you make a binding offer.
OUN® reads the site documents for you and delivers a plain-language analysis within 24 hours. We are 100% on your side – we don’t sell the property to anyone.